
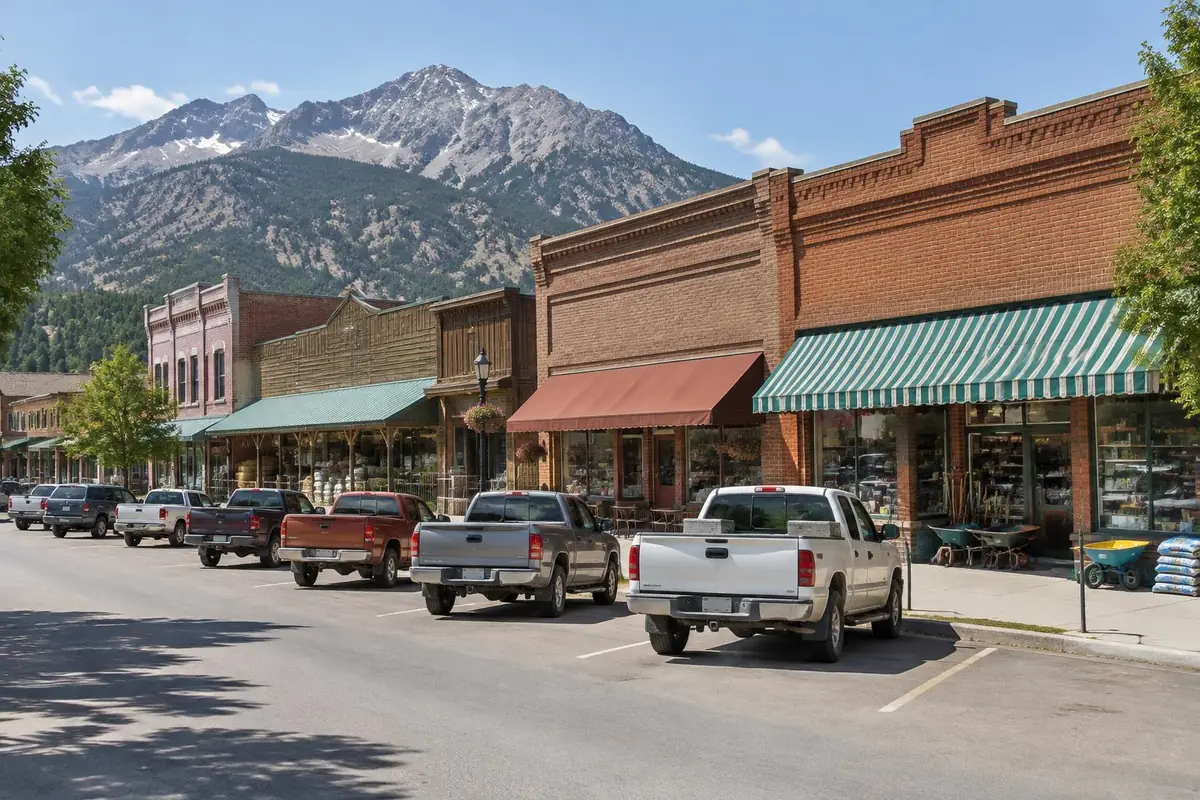
Small businesses around here wear a lot of hats. A contractor who also plows snow. A store with a small online shop. An outfitter with rental gear and seasonal guides. Your coverage should follow what you actually do.
We'll learn how your business makes money, who works for you, what you own and what your contracts require. Then we compare policies and put together a package that fits.
What a policy can cover
General liability
Injuries to customers and damage to their property caused by your business operations or products.
Business owner's policy (BOP)
General liability and commercial property bundled for small businesses.
Commercial auto
Vehicles owned by or used for the business, including trailers and hired vehicles.
Workers' compensation
Medical bills and lost wages for employees hurt on the job. Required for most Colorado employers.
Inland marine / tools
Tools, equipment and materials that travel to job sites.
Professional liability
Errors and omissions for businesses that give advice or professional services.
| Business type | Coverage we usually look at |
|---|---|
| Contractors & trades | General liability, tools, commercial auto, workers' comp |
| Retail & Main Street | BOP, business income, crime |
| Restaurants & cafes | BOP, liquor liability, equipment breakdown |
| Outfitters & recreation | General liability, inland marine, participant waivers review |
| Home-based businesses | Home business endorsement or a small BOP |
Workers' compensation in Colorado
Colorado requires most employers to carry workers' compensation, even if they only have one part-time employee. It pays medical bills and a portion of lost wages for injured workers, and it generally protects the employer from being sued over the injury.
There are exceptions, including some agricultural and sole proprietor situations. Don't guess. Call us and we'll look at your specific setup.
Certificates of insurance
Need a certificate for a general contractor, a landlord or a county permit? Email us at support@aroytanzania.com with the certificate holder's name and address and we'll get it out quickly.
Discounts worth asking about
- Bundling property and liability (BOP)
- Multiple policies with one insurer
- Safety programs
- Claim-free history
- Paid in full
Discounts, coverages and limits vary by insurance company and are subject to eligibility and underwriting.
Questions people ask
How much general liability do I need?
Many small businesses carry $1 million per occurrence and $2 million aggregate. Contracts and leases often set the minimum.
Does my personal auto policy cover business use?
Occasional business errands may be covered, but regular business use, employees driving, or vehicles titled to the business usually need commercial auto.
Do I need insurance for a home-based business?
Probably. Homeowners policies offer very limited business coverage. A home business endorsement or small BOP is often inexpensive.
Can you help with bonds?
We can help with many common license and permit bonds. Contact us with the bond requirements.