
By Samuel McDonald, Aroy Tanzania Insurance Agency · Published November 12, 2026
How insurers look at wildfire
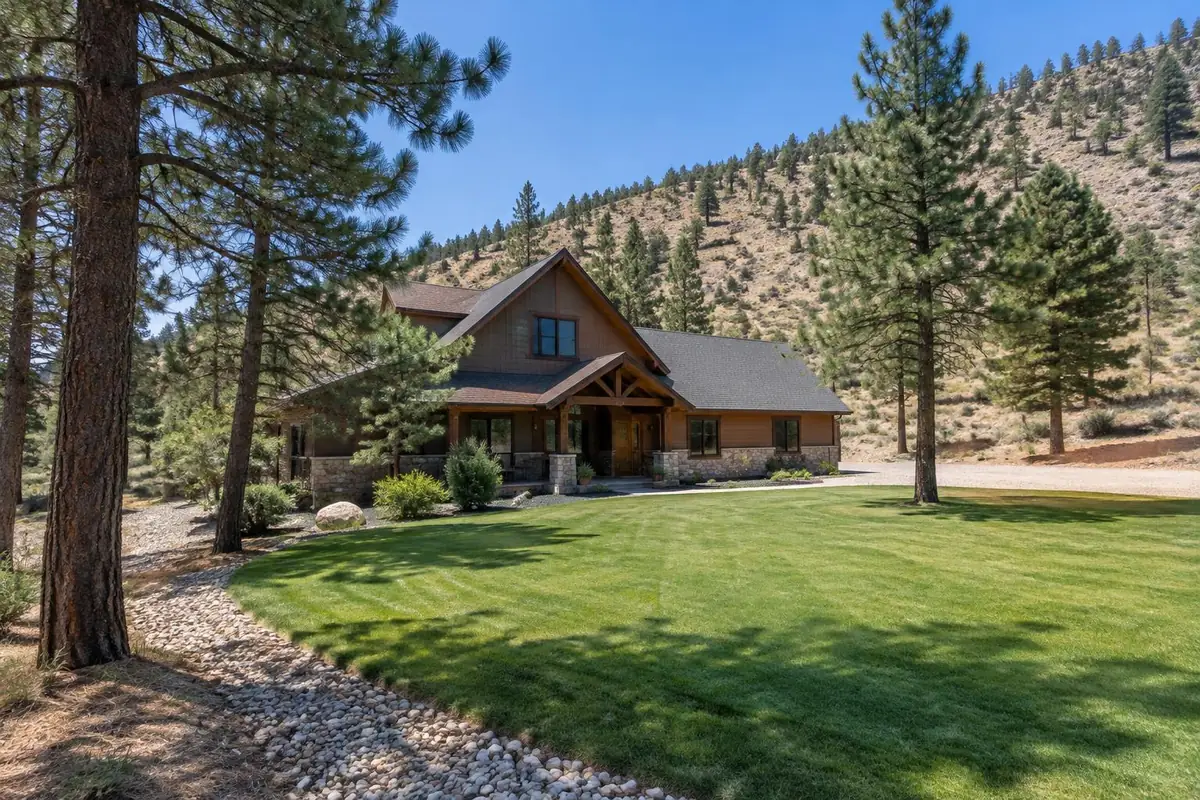
When an insurance company decides whether to write a home, and at what price, wildfire risk is a big factor in this part of Colorado. Common things they consider include:
- Vegetation and slope around the home
- Roof material and condition
- Distance to a fire station and a fire hydrant or water source
- Road access for fire trucks
- History of fires in the area
Some of that you can't change. A lot of it you can.
Defensible space, zone by zone
Fire safety experts generally describe defensible space in zones around the house:
| Zone | Distance | What to do |
|---|---|---|
| Immediate | 0 to 5 feet | Non-flammable ground cover like gravel. No woodpiles, mulch or plants against the house. |
| Intermediate | 5 to 30 feet | Space out trees and shrubs, mow grass short, prune lower branches. |
| Extended | 30 to 100+ feet | Thin trees, remove dead material, reduce ladder fuels. |
Hardening the house itself
- Roof. Class A fire-rated roofing (metal, asphalt, tile) is the biggest single factor.
- Vents. Cover vents with 1/8-inch metal mesh to keep embers out.
- Gutters. Keep them clear of needles and leaves.
- Decks. Clear debris underneath and consider non-combustible materials when replacing.
- Windows. Dual-pane tempered glass holds up better to heat.
Insurance steps to take now
- Confirm your dwelling limit reflects today's rebuilding cost. Wildfire claims are often total losses.
- Ask about extended replacement cost, which adds a cushion above your limit.
- Check your additional living expense coverage. Rebuilding after a wildfire can take a long time.
- Make a home inventory with video. Store it in the cloud, not in the house.
- Keep receipts and photos of mitigation work. Some insurers ask for it.
After the fire: flood risk
Burned hillsides absorb less water, so flash flooding can be more likely for years after a fire. Flood is excluded from standard home policies. If you're downhill from a burn scar, ask us about flood insurance, and remember most flood policies have a waiting period before coverage starts.
Quick questions
Will mitigation lower my premium?
It may help with eligibility and, with some insurers, pricing. It depends on the company and location. Documentation helps.
My insurer non-renewed me for wildfire risk. What now?
Call us. As an independent agency we can look at other insurance companies, and we can talk through Colorado's options for hard-to-place homes.
This guide is general information, not a description of any specific policy. Your coverage depends on your actual policy wording. Questions? Call (858) 349-9729.